The Real House Edge Isn't in the Games — It's in How You Load Your Account
Most players walk into a casino — or open an app — convinced the danger lives inside the games. The slots, the blackjack tables, the roulette wheel. That's where the house gets you, right? Maybe not. A growing body of behavioral economics research is pointing somewhere far less dramatic: the deposit screen.
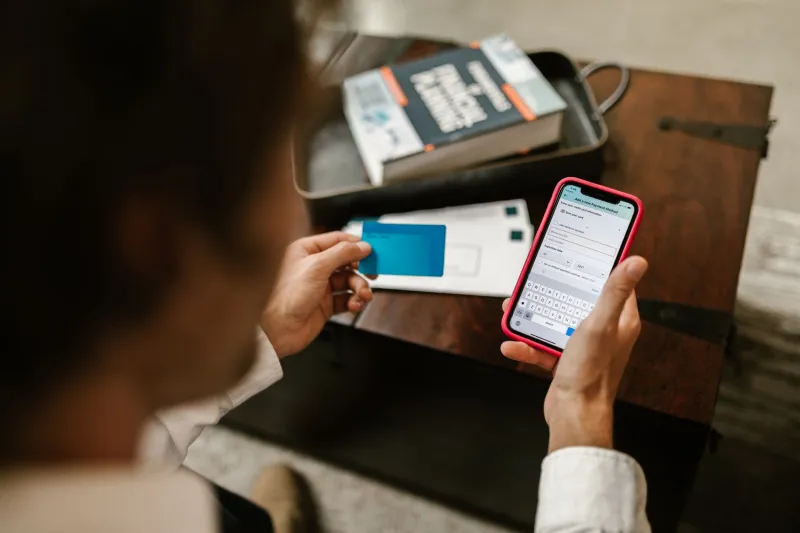
Specifically, the moment you tap "Add Funds" and your saved card auto-fills, your preferred amount pre-populates, and the money moves in about four seconds flat. That moment — frictionless, forgettable, almost invisible — may be costing US players more than any single game on the platform.
What Behavioral Economists Mean by "Friction"
In economics and psychology, friction refers to any obstacle that slows down a decision. It sounds like a bad thing. Nobody wants friction. But when it comes to financial decisions, a small amount of friction is actually protective. It gives your brain a beat to catch up with your impulses.
Think about why ATMs used to make you wait a few seconds before dispensing cash. Or why your 401(k) requires multiple confirmation steps before you can make a withdrawal. Those delays aren't technical limitations — they're intentional design choices rooted in the understanding that humans make worse financial decisions when the process feels effortless.
Online gaming platforms have spent years engineering the opposite experience. Saving payment methods, enabling one-click deposits, pre-filling amounts based on your history — all of it is built to minimize the mental gap between "I want to play" and "money is in my account." The result, according to researchers, is that players routinely fund their accounts at two to three times the amount they'd consciously choose if the process required more steps.
The $5,000 Problem in Plain Language
Here's a scenario that plays out thousands of times a day across US gaming platforms. A player sits down for what they mentally frame as a casual session. They're thinking $50, maybe $100. They open the app, hit deposit, and the interface offers them a pre-selected $200 button — the same amount they used last time. Their card is already saved. It takes one tap. They're in for $200 before they've consciously committed to it.
Multiply that pattern across a month of sessions, and a player who intended to spend around $400 has actually deposited closer to $1,600. Do that for a quarter, and you're staring at a number that can easily climb past $5,000 — not because the games cheated them, but because the deposit flow nudged them into larger stakes before the session even started.
This isn't a conspiracy theory. It's a documented behavioral pattern called "payment decoupling" — the psychological separation of spending from its consequences when a transaction feels abstract or automatic. Credit cards produce the same effect compared to cash. Digital wallets amplify it further. And gaming platforms, by design, push it to an extreme.
How Platforms Engineer the Path of Least Resistance
Spend some time actually analyzing how major gaming sites structure their deposit flows and a few things become obvious pretty quickly.
First, the default deposit amounts are almost never the smallest option. Platforms surface $100, $200, or $500 as easy-tap choices, with smaller amounts requiring the player to manually enter a custom figure. That extra step — typing in $25 instead of tapping $100 — is just enough friction to make the smaller choice feel like more work.
Second, saved payment methods remove what researchers call the "pain of paying." When you have to enter your card number, expiration date, and CVV, you're physically reminded that real money is moving. When your card is saved and it's just a tap, that reminder disappears entirely. Studies on consumer spending consistently show that payment pain reduction leads to higher average transaction amounts.
Third, many platforms use deposit history to prime you toward larger amounts. If you deposited $150 last Tuesday, the interface might surface that as a suggested amount this time — not because it's in your best interest, but because the data shows repeat deposits tend to match or exceed prior amounts when the suggestion is present.
Why This Hits US Players Particularly Hard
American players come to online gaming with a few cultural factors that make them especially susceptible to frictionless deposit design. The US is already a heavily card-centric economy — most Americans are deeply comfortable with digital payments and have multiple cards saved across dozens of platforms. The muscle memory of one-tap transactions is deeply embedded.
Combine that with the relatively recent expansion of legal online gaming across US states, and you've got a large population of players who are newer to the environment and haven't yet developed the habits that protect more experienced players. New players, research consistently shows, are the most responsive to interface design cues — including deposit prompts.
There's also the competitive pressure between platforms. As more states legalize online gaming and the market gets crowded, operators compete aggressively on "ease of use" as a selling point. Frictionless deposits get marketed as a feature, a convenience, a sign that a platform respects your time. The player hears "easy" and thinks that's good for them. In the context of deposits, it often isn't.
Practical Ways to Put Friction Back in Your Deposit Flow
The good news is that you don't need the platform to change. You can rebuild intentional barriers yourself, and it doesn't require willpower — just a few deliberate setup choices.
Remove your saved payment method. It takes about 90 seconds to delete a saved card from a platform. When you have to re-enter your details each time you deposit, you reintroduce the payment pain that makes you think twice. It's mildly inconvenient. That inconvenience is doing real work for your bankroll.
Set a session budget before you open the app. Not a vague mental note — an actual number, written down or typed into your phone's notes app. When you've committed to a number in advance, you're far less likely to let a pre-filled deposit field override it.
Use a separate, dedicated funding method. A prepaid card or a standalone account that you transfer a fixed amount into each week creates a hard boundary. When it's empty, it's empty. The platform can't auto-fill what isn't there.
Ignore the suggested deposit amounts entirely. Always tap "custom amount" and type in what you actually decided to spend. Every single time. It sounds small, but that deliberate action reconnects you to the financial reality of the transaction in a way that tapping a pre-filled button simply doesn't.
Give yourself a 60-second rule. Before confirming any deposit, wait one minute. Set a timer if you have to. Behavioral research shows that even a brief mandatory pause significantly reduces impulsive spending decisions. You're essentially building your own friction.
The Bigger Picture
None of this means that easy, well-designed gaming platforms are inherently bad. There's genuine value in interfaces that don't waste your time. But there's a meaningful difference between a platform that makes games easy to play and one that makes it easy to spend more than you meant to before the games even start.
The smartest players understand that the gaming experience begins the moment they open the app — not when the first bet is placed. And the most important decision they make isn't which game to play or how to size their bets. It's how much money actually makes it into their account in the first place.
Control that number intentionally, and you've already beaten the house at its own pre-game.